downloadGroupGroupnoun_press release_995423_000000 copyGroupnoun_Feed_96767_000000Group 19noun_pictures_1817522_000000Member company iconResource item iconStore item iconGroup 19Group 19noun_Photo_2085192_000000 Copynoun_presentation_2096081_000000Group 19Group Copy 7noun_webinar_692730_000000Path
Skip to main content
Default Banner Image

Technology and Trends

[caption id="attachment_12359" align="alignright" width="300"] (Courtesy: PRNewsfoto/QuickLogic Corporation)[/caption] Some great pieces of FD-SOI news from QuickLogic. The company recently demonstrated its ultra-low power ArcticPro™ embedded FPGA (eFPGA) solutions at the GlobalFoundries Technology Conferences in Santa Clara, California, Munich and Shanghai. The technology is available now. ArcticPro is the industry's first eFPGA offering for GF's 22FDX® process (btw they've been shipping it in volume for GF's 65nm and 40nm bulk processes for years). The company says its ultra-low power eFPGA architecture and mature software offer semiconductor and system companies the ability to integrate programmable hardware accelerators to lower power consumption and the flexibility to reconfigure a device's functionality in the field. [caption id="attachment_12360" align="alignleft" width="300"] (Image courtesy: QuickLogic)[/caption] QuickLogic has also announced that the technical university ETH Zurich will integrate QuickLogic's ArcticPro technology onto the university's PULP platform. PULP is a silicon-proven open-source parallel platform for ultra-low power computing created with the objective of delivering high compute bandwidth combined with high-energy efficiency. ETH will become the first licensee of eFPGA technology from QuickLogic on GF's 22FDX process node. They will develop an SoC integrating ETHZ's open-source RISC-V cores and eFPGA technology, enabling users to offload critical functions from the processor(s) and implement them in eFPGA fabric. This approach creates multiple hardware co-processors that increase system efficiency and performance while decreasing power consumption. "The main goal of the PULP program is to use a multi-disciplinary approach to achieve extremely high-power efficiency for computing applications," said QuickLogic CTO Dr. Timothy Saxe. "QuickLogic has a tremendous depth of experience in achieving low power consumption across a broad range of applications, including AI and IoT at the edge and security, and we look forward to contributing what we've learned along with our eFPGA technology to this groundbreaking initiative in low power computing." ETH's PULP platform with the fully integrated eFPGA is expected to be available Q1' 2019. QuickLogic is part of GF's fast-growing FDXcelerator™ partner ecosystem, offering customers ultra-low power (eFPGA) Intellectual Property, complete software tools and a compiler.
Read More
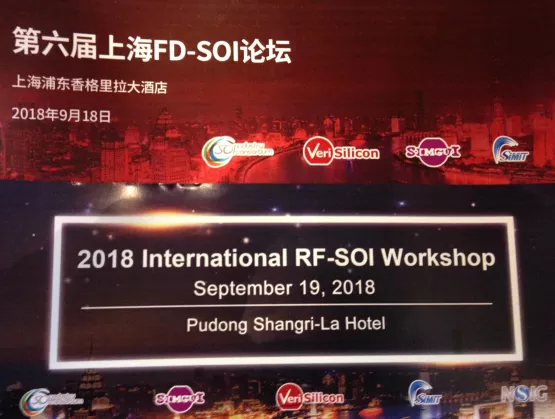
Excellent news and exciting applications made headlines at the recent FD-SOI and RF-SOI events in Shanghai. During the FD-SOI day, Amazon/Blink and Intellifusion shared news about their new chips, and we got updates from GF and Samsung. The RF-SOI day featured a great talk with details about China Mobile's 5G plans, and peeks at Nokia's groundbreaking approach and Qorvo's outlook. [caption id="attachment_12354" align="alignright" width="300"] (Photo courtesy: Verisilicon)[/caption] The hall was absolutely full – with over 300 people attending each day. The FD-SOI event was by invitation only, and there were far more people wanting to attend than there was room for, even given the big room in which the events were held. The events got excellent coverage in the China tech press. For example, EEWorld started with an overview article and added five supporting pieces zooming in on key presentations and companies: one on GlobalFoundries, one on Samsung, one on Verisilicon, and two on Soitec (CEO and top exec interviews). These pieces are in Chinese, but just open the links through your favorite translation site. Many of the key slides are captured in these articles, so if you can't wait for the ppts to be posted on the SOI Consortium website, you can get some quick previews now. The Verisilicon PR folks also wrote up highlights of the FD-SOI event in real time with lots of great pictures – you can read that here. Many thanks to that team, too, for flagging the coverage in the China press and posting it on their WeChat account. On the RF-SOI side, the Simgui folks wrote that up – you can read it here. They also sponsored a gala dinner with awards given to Qorvo and SmarterMicro – you can read about that here. Most of the presentations will be posted on the SOI Consortium website over the next few weeks, at which point we'll cover them in-depth here at ASN. But for now, here's a quick round-up of some of the highlights. FD-SOI Highlights [caption id="attachment_12347" align="alignright" width="300"] (Courtesy: Blink, Verisilicon)[/caption] Boston-area based Blink, which makes very popular home security systems, was recently bought by Amazon (see their current product page here). They just taped out a new chip on Samsung's 28FDS FD-SOI technology, and they're really happy about it. “I believe for battery powered devices at home, FD-SOI is the way to go,” said Yantoa Jia, Head of ASIC China Ops at Blink. Their goal in the move from 55nm bulk to 28nm FD-SOI was to double battery life, add features and control costs: and they did it. Even adding two more CPU cores and lots more features, “The power drop is fantastic,” he said. Design was no problem, he continued, and there was plenty of IP. Once the new generation is officially announced, he promised to sit down with ASN and give us more details. Attendees also heard about a new chipset from Intellifusion, which is putting its face recognition technology onto GlobalFoundries' 22FDX FD-SOI with design house Verisilicon. CEO Nin Chen gave an impromptu talk about how their technology is used to find missing people and property. The new chip, which is especially designed for use in cities, is network-to-cloud leveraging AI. For his part Thomas Morgenstern, GlobalFoundries SVP and GM of the Dresden Fab 1, said they're seeing high yields and increasing capacity for 22FDX. The marketing and manufacturing ecosystem has been built around the fab in Europe. Now, he said, the key is to build an FD-SOI ecosystem in China. The market needs of China largely parallel those of Europe, he noted, for performance and efficiency at the right cost point. The ecosystem enables fast time-to-market and 1st-time-right. [caption id="attachment_12343" align="alignleft" width="300"] (Photo courtesy: Cadence)[/caption] Samsung SVP Gitae Jeong sees their FD-SOI technology as the right solution for the 4th Revolution, which includes everything from energy harvesting to self-driving cars. They've just taped out their first 5G mmWave cellular chip on 28FDS, he revealed. eMRAM is looking very good, only requiring three additional masks and getting stable yields from -40o to 105oC. 18FDS is on schedule, with PDK 0.5 now being released, and 1.0 on track for release in March 2019. They expect a very fast ramp, and are looking at a 35% area reduction, power cut in half and performance up 22% compared to 28FDS. RF-SOI Highlights [caption id="attachment_12350" align="alignright" width="300"] China Mobile, Project Manager Danni Song (Photo courtesy: Simgui)[/caption] When China Mobile talks, the world listens. Project Manager Danni Song presented again this year (she gave a great talk last year, too). China has a very ambitious 5G project underway, and under two years in which to roll it out. The biggest challenges are power consumption and cost (a problem made worse by the additional power amplifiers needed for MIMO). Can RF-SOI help solve these challenges, she asked? One thing she did clarify during the panel discussion was with respect to the mmWave part of the 5G puzzle. Their initial 2020 rollout will only focus on sub-6GHz, with mmWave following a year or two later. Michael Reiha, Head of RFIC R D at Nokia Mobile Networks clarified the worldwide 5G rollout during the panel discussion. Different locations on the planet have different histories and needs, so will rollout 5G in different ways. For historical reasons (and a lack of choice), the US will lead with mmWave, he said. Europe, meanwhile, will focus on 24GHz to meet the needs of automotive radar. In his presentation, Reiha described Nokia's approach to power amplifiers (PA), which is very different from what others are doing. With RF-SOI, he said, you can add sensors and logic for a level of preventative care, so you can gauge and protect your equipment using AI. He believes this disruptive approach will put them two years ahead of the industry, enabling massive MIMO to be deployed in dense urban areas with 60% lower power consumption and 50% savings in material costs. Go read about their Reefshark tech, he urged, which he says will beat GaAs. “The future is very bright with RF-SOI,” he concluded. “I can state that with confidence.” [caption id="attachment_12351" align="alignleft" width="300"] Julio Costa, Director of Technology Development, Qorvo (Photo courtesy: Simgui)[/caption] Julio Costa, Director of Technology Development at Qorvo sees it differently. Traditionally a GaAs house, all their RF-SOI work is fabless. While RF front end modules (FEMs) are loaded with RF-SOI, he said, and are a big winner for antenna tuning, Qorvo still sees GaAs for high-efficiency amplifiers and envelope tracking. But, he said, it will be a battle. GaAs wins in terms of area and power consumption he contends, but adds that SOI wins in terms of cost. Power levels, he predicts, will be the determining factor. So that's the quick overview – we'll drill down into the presentations as they're posted, so stay tuned!
Read More
With one of the oldest and largest public education systems in the developed world, how well does the US public education system serve the global electronics industry? Public education in the US has had time on its side. In 1635 the Boston Latin School became the first public school in the US. Boston Latin was originally a boys-only secondary school that taught Greek, Latin and the humanities. It wasn’t until 1918, however, that the US government required all children to obtain at least an elementary-school education – available to them through free public schools. As public education increasingly served the masses rather than just the elite, a balance of humanities, mathematics and science began to replace the classics.While free public education in the US got a comparatively early start, most American students score lower in science and math than students in many other developed nations. According to a 2017 Pew Research Study, 15-year-old American students ranked 24th in the world in international standardized age-group science testing and 38th in the world in standardized mathematics testing. While test scores are just one measure of proficiency, do they in some way reflect a lack of motivation to study science and math because of students’ unfamiliarity with STEM careers? Source: Pew Research. See article. Make STEM RelevantIf we want the US to remain a leader in the global electronics industry, we need to pay attention to the disconnects between academics and workforce development. We must help show students at an early age that STEM careers can be exciting, creative and fulfilling, and that math and science are essential to STEM.Ways to Get InvolvedWhether you work for a large publicly traded electronics manufacturer, an equipment or materials supplier, a foundry or a startup, you can take action to support student engagement in STEM. Here are a few ways to get involved:Participate in Community Programs One fun way to inspire budding technologists is to sponsor one of the FIRST programs for students. These age-segmented competitive programs range from FIRST LEGO League, Jr. Challenge for six-ten year-olds to FIRST Robotics Challenges for high school and college students, giving you the opportunity to sponsor a team or even to coach.Our company sponsors Team TNT, a Southern Oregon-based team that placed among the world’s top high school robotics teams at the spring 2018 world championships. We also brought two members of Team TNT to SEMICON West 2018, where they attended SEMI’s three-day High Tech U and presented their insights on building their FIRST Challenge robot at the Smart Workforce Pavilion. Margaux Quady (L) and Matthew Mills (R), Team TNT members, presented at SEMI’s Smart Workforce Pavilion at SEMICON West (Rogue Valley Microdevices) Concerned about the dearth of girls interested in STEM — and the small numbers of women in engineering careers? Look for your local equivalent of the Advocates for Women in Science, Engineering, and Math (AWSEM) Symposium, a day-long program for middle school girls. One of our engineers, Jennifer Devin, gave a hands-on workshop on deconstructing smartphones to showcase the silicon chips inside them. If you cannot find something like AWSEM, check out national programs such as the Society for Women Engineers (SWE)’s SWENext program for girls ages 13-18 as well as Girl Powered.Partner with Local SchoolsYou would be surprised at the opportunities to present what you do in the classrooms of school-age children. Take after Allyson Hartzell, managing engineer at Veryst Engineering in Needham, MA. Allyson speaks with students in her local elementary schools of Somerville and Cambridge, Massachusetts because she thinks that we must reach younger children to get them excited about STEM learning. “Waiting until middle school or high school to help students visualize the real-world appeal of STEM careers is just too late,” said Hartzell. “I’ve had amazing experiences working with local elementary-school students. Students become engaged when you show them real-world examples such as electron micrographs of MEMS.”Many middle schools and high schools also look to their communities to provide tutors in STEM subjects. Check with the community liaison at your local school to get started.Engage in Internship ProgramsInvolvement doesn’t stop in the K-12 grades. Seek out a local university’s internship program and hire some interns in that program to work at your company. The interns will gain valuable applied experience in your environment, and you might find young engineers who would love to join your company after they graduate. Oregon’s MECOP, an engineering-specific internship program founded on close industry-university collaboration, has been amazing for our recruitment. Some of our finest engineers were once in the MECOP program, including our engineering manager.Anything you do to get involved in inspiring coming generations of students to explore STEM — no matter how small your action — will make a positive difference in helping US students become better prepared to enter a technology-focused workforce. Through collaboration and creativity, we can help US companies keep the global electronics industry moving toward greater innovation. Jessica Gomez, CEO and co-founder of Rogue Valley Microdevices, entered the semiconductor manufacturing field in 1998 at Standard Microsystems Corporation of Hauppauge, New York where she acquired valuable knowledge in both semiconductor processing and production management. Jessica also held positions at Integrated Micromachines and Xponent Photonics prior to co-founding Rogue Valley Microdevices in 2003. As head of a technology company, Jessica recognizes the criticality of workforce development – and has become an advocate of STEM education. Rogue Valley Microdevices supports STEM initiatives for middle-school girls, a competitive robotics team for high school students, and a college internship program specifically for engineers.Expanding her energies beyond the company she co-founded, Jessica is also applying her passion for change to politics. She is currently campaigning for the Oregon State Senate.For more information, visit Rogue Valley Microdevices.
Read More
Over the last three years the number of battery-operated electronic-component solutions for the Internet of Things (IoT) and Industrial IoT (IIoT) applications has been increasing steadily. This trend will continue for years to come, particularly with the growing popularity of mobile devices of all flavors. Addressing power consumption for battery-powered always-on IoT/IIoT devices – which rely on dozens of electronic components, including sensors — is critical to their commercial success.The demand for ultra-low-power sensors has accelerated the race to squeeze every last mW from components. Compared to previous-generations of sensors, semiconductor suppliers have managed to drastically reduce power by as much as 50%-60% over older solutions. Leveraging new state-of-the-art analog design techniques, we have effectively optimized capacitive readings of MEMS structures. How effective are they? We estimate that with the right mix of our company’s power-saving technologies, it is possible our customers could save 3MW/year globally[1].What’s next?While the semiconductor industry continues to investigate novel technologies, approaches and analog IP for greater energy efficiency, we believe that bigger gains in reducing power consumption will come from thinking at the system level. The sensor node is a good place to start.A typical IoT node is composed of a set of sensors, a microcontroller, a radio frequency (RF) link, and a power-supply system, often based on Li-Po batteries.Of these, the microcontroller and RF link consume the most energy and, in the RF link, power consumption is a function of the distance between end point and receiver and of the amount of data transmitted. Thus, at longer distances reducing the amount of data transmitted can save power. We can achieve this by including some pre-elaboration capabilities on-board and by extracting more meaningful information from the raw sensor data.We address this by moving some computation and data analysis inside the sensors, where smart hardware “digital blocks” perform faster and more efficiently than software-based routines running in the microcontroller. We can achieve this by using dedicated hardware resources to reduce overall system power consumption. The beauty of this solution is that it allows the microcontroller to operate in low-power states by only transmitting significant information in batches. The SensorTile development kit can speed up prototyping of ultra-low-power IoT devices by integrating an ultra-low-power MCU and BlueNRG Bluetooth radio with sensors. Some examples of these advanced digital blocks are the Advanced Embedded Pedometer, the Finite State Machine and Decision Tree, and Compressed FIFO in an IMU.The Advanced Embedded Pedometer is a hard-wired step counter that works independently inside the sensor, without CPU intervention: By comparing sensor outputs to pre-defined and -loaded patterns, it autonomously decides whether the user is walking or running to start and stop counting the user’s steps. The sensor then makes this information available to the microprocessor for further elaboration or for simple notification to the user.The Finite State Machine and Decision Tree are new functions dedicated to pattern recognition (machine learning) and decision-making: They can perform complex classifications and state detection, and can send dedicated warning and signaling to the microprocessor. A good real-world example is industrial predictive maintenance, where the sensor can categorize and identify different malfunctioning states in the equipment before waking the microprocessor to react.Our products, on average, save about 1 mA (1e-3) over competitive devices or over our previous-generation parts. So 2.0 x 1e-3 x 1.5e9 = 3MW. Programmable Sensor and Decision Tree Finite State Machine Integrating programmable sensors and decision trees as well as finite state machines in the sensor allows the sensor to do more of the work while the MCU sleeps. Source: STMicroelectronics Another example is compressed FIFO (first-in, first-out) buffer, which can store sensor data in the sensor, not in raw format, by using efficient compression algorithms. In addition to saving memory (and therefore silicon area) inside the sensor chip, it also saves power by reducing the number of bytes transferred to the processor and by shortening the communication data flow, which reduces processor-active time.These examples – the Advanced Embedded Pedometer, the Finite State Machine and Decision Tree, and compressed FIFO buffer – are just some showing that we can develop low-power IoT/IIoT devices through intelligent management of sensors, microcontrollers and other components in any given system. Your starting point is an IoT/IIoT node that lets you selectively allocate some power-hungry tasks — such as computation and data analysis — to sensors instead of the microcontroller. Leveraging data blocks that reside in the sensors alleviates the microcontroller’s typical power drain, allowing the microcontroller to operate with maximum efficiency.[1] ST sells about 1.5 billion pieces/year (1.5e9), which typically run from a 2V supply. Luca Fontanella joined ST Microsystems in 1995 as an analog designer. In 2001 he joined the MEMS team in a marketing role and today he is marketing manager in the MEMS Sensor Division. Luca has contributed to 25+ international patents and has presented at multiple conferences. He earned a degree in Electronic Engineering from Padua University. Simone Ferri joined STMicroelectronics in 1999 as Central R D engineer, moved to the Audio Division as a digital designer and is now director of the Consumer MEMS Business Unit. He holds a degree in Electronic Engineering and an MBA from the Polytechnic of Milan. _______________________________________________________________________________________________Brush up on the latest MEMS and sensors trends and gain a new perspective on emerging applications. Register today!
Read More
Materials innovation has always been vital to the semiconductor industry. In the past, it was high-κ gate dielectrics. Today, Cobalt is seen as a replacement for Tungsten in middle-of-line (MOL) contacts.What materials innovation will the future bring?A likely answer is Graphene, the wonder material discovered in 2004.Graphene is one atomic layer of carbon, the thinnest and strongest material that has ever existed. It is 200 times stronger than steel and the lightest material known to man (1 square meter weighing around 0.77 mg). It is an excellent electrical and thermal conductor at room temperature with an electron mobility of ~ 200,000cm2.V-1.s-1. At one atomic layer, graphene is flexible and transparent. Other notable properties of Graphene are its uniform absorption of light across the visible and near infrared spectrum and its applicability towards spintronics-based devices.Graphene and Moore’s LawMoore’s Law scaling can be broken down into 4 key areas: Lithography FET Advanced Packaging (2.5D and 3D IC) Interconnect Material Solutions for upcoming nodes are starting to emerge in the first two areas (EUV and Nanowire- or Nanosheet-based FET respectively). Graphene play an important role in the latter two areas. For advanced packaging, Graphene can be used as a heat spreader (to lower overall thermal resistance), or as an EM shield (to lower crosstalk) as part of a 3D IC package.Active Graphene device layers can potentially be stacked on top of each other using a low-temperature transfer process ( 400°C) to allow for a dense heterogeneous “memory near compute” configuration. This is an area DARPA is actively researching as part of its new $1.5 billion Electronics Resurgence Initiative.Regarding interconnects, Copper interconnects are running out of steam and becoming a major IC bottleneck (projected 40% total delay for 7 nm node). Graphene’s high electron mobility and thermal conductivity make it an attractive interconnect material for MOL and back-end-of-line (BEOL), especially at line widths 30 nm.Graphene Device ApplicationsGraphene-based semiconductor applications are already starting to hit the market. A fully integrated optical transceiver (with a Graphene modulator and photodetector) operating at 25 Gb/s/channel was on display at the recent Mobile World Congress in Barcelona. San Diego-based Nanomedical Diagnostics is selling a medical device that uses a Graphene biosensor. Europe-based Emberion is building Graphene optoelectronic sensors that might find a home in LIDAR applications, where there is currently a focus on improving sensing in low-light conditions.What will the overall Graphene roadmap in the semiconductor industry look like? The history of ion implantation serves as a good example of how a fundamental scientific discovery moves from the lab to the foundry floor.The dominant view in the semiconductor industry at the time was that ion implantation would not work in practice (vs. thermal diffusion) and that, if it did, it would only marginally improve the manufacturing yields of existing products. There was nothing obvious about the transfer of ion bombardment techniques from nuclear physics research to semiconductor production.Varian (led by British physicist Peter Rose) built a new, advanced ion implant tool that Mostek (DRAM manufacturer based in Texas) was able to use to create MOS ICs with clear competitive advantages. The successful collaboration between Varian and Mostek was the turning point in the development of ion implantation as a major semiconductor manufacturing process. Over the next few years, semiconductor firms used ion implantation in a growing number of process steps and, by the late 1970s, it became one of the main processes used in semiconductor manufacturing.Likewise, the Graphene world needs to work closely with the semiconductor industry to develop the tools and techniques required to solve fundamental issues around Graphene growth (good uniformity over large area, low defect density) and Graphene transfer (high throughput, CMOS compatible). It is only then will we fully realize a future that includes 2D materials.The first step in this process is cross-industry education and initiating the dialogue between semiconductor industry and graphene companies. The National Graphene Association will be hosting the largest gathering of graphene companies and commercial stakeholders at the Global Graphene Expo Conference, October 15-17, 2018, in Austin, Texas.Learn more about graphene at the upcoming Global Graphene Expo Conference with dedicated panels of experts and investors, and roundtable discussions on how Graphene will impact the semiconductor industry. The event promo code is SEMINGA. About the AuthorAnand Chamarthy is the CEO and Co-Founder of Lab 91, an Austin-based startup that is working towards Graphene/CMOS integration at the foundry level. Anand can be reached at [email protected]. About the National Graphene AssociationThe National Graphene Association is the main organization and body in the U.S. promoting and advocating for commercialization of graphene and addressing critical issues such as standards and policy development.
Read More
The presentations from the SOI Consortium sponsored workshop held during Semicon West are now posted and freely available on the website – click here to see the full agenda with links to the presentations. The workshop, entitled 4G/5G Connectivity: Opportunities for the SOI Supply Chain, was well-attended and generated excellent discussions. If you don't have time to look at all of the ppts, here are quick overviews. Market Overview and FD SOI Opportunities, by Handel Jones, CEO, IBS. Handel Jones is an industry veteran, China expert and longtime follower of the SOI ecosystem. High performance with low power consumption are the key requirements for the continued growth in the semiconductor industry, he said, making FD-SOI the right choice for a wide range of products. Here's how he sees it: [caption id="attachment_12312" align="alignleft" width="300"] (Courtesy: IBS and SOI Consortium)[/caption] He estimates the yearly TAM (total available market) for FD-SOI based products in the range of $46 billion over the next 10 years, largely driven by needs for ultra-low power and RF integration. He goes on to break out volumes by applications (including ISPs – image signal processors; and CIS – CMOS image sensors), foundry markets by feature dimension and to map out technology trends. Mobile Radio Transformation in the Age of 5G: A Perspective on Opportunities for SOI, Peter Rabbeni, Vice President, Globalfoundries. Peter Rabbeni is an RF expert par excellence, having overseen the shipping of over 35 billion RF-SOI products to date. In his presentation, he details how 5G NR (New Radio) sub-6GHz frequency band specifications significantly increase frequency range and channel bandwidth, and how new band support and MIMO complexity and die size per handset are driving complexity in RF FEMs. Furthermore, 5G/mmWave phased arrays are driving a paradigm shift in the approaches that can be taken, he explains, so greater integration is needed. Here's a great slide showing where GF's two main SOI technologies come into play: [caption id="attachment_12311" align="alignleft" width="1000"] (Courtesy: GlobalFoundries and SOI Consortium)[/caption] Empowerment of 5G with SOI-Based Technologies, Emmanuel Sabonnadière, CEO, Leti-CEA. [caption id="attachment_12310" align="alignleft" width="300"] (Courtesy: Leti and SOI Consortium)[/caption] Working in partnership with industry leaders around the world, Leti has been the research powerhouse behind all things SOI since the early 1980s. In fact Reuters ranks them #2 in their most recent list of the World’s Most Innovative Research Institutions. This presentation reviews the key technical benefits of FD-SOI for IoT and IMT (that's international mobile communications, btw). Engineered Substrates – at the Foundation of 5G, Thomas Piliszczuk, Executive Vice President, Soitec. This presentation really puts the context around engineered substrates. Here are two excellent and useful slides here that identify which engineered substrates go where in the 5G world, and the engineered substrates that Soitec provides. Check these out: [caption id="attachment_12309" align="alignleft" width="1000"] (Courtesy: Soitec and SOI Consortium)[/caption] [caption id="attachment_12308" align="alignleft" width="1000"] (Courtesy: Soitec and SOI Consortium)[/caption] Ultra-thin Double Layer Metrology with High Lateral Resolution, Bernd Srocka, Vice President, Unity GmbH. [caption id="attachment_12307" align="alignleft" width="300"] (Courtesy: Unity and SOI Consortium)[/caption] In case you're not familiar with them, Unity provides a wide range of solutions in metrology and inspection. Both the top silicon layer and BOX layer of wafers for FD-SOI applications have draconian requirements that have required new approaches in metrology to ensure the thickness and homegeneity control of these very thin layers. China 5G Plan and SOI Ecosystem, Jeffrey Wang, CEO, Simgui. Shanghai-based Simgui partners with Soitec, using SmartCut™ technology for the production of RF-SOI wafers. It is doubling its capacity to reach 400K over the next year, and expanding into 300mm. China is aggressively working on 5G and plans to deploy 5G commercialization in 2020. Jeff Wang's is a terrific presentation detailing the rollout. (BTW, in addition to the massive funding effort underway, the government created the National Silicon Industry Group (NSIG) to support the semiconductor material ecosystem in China. You'll want to keep up with what's going on here). Here's the slide that summarizes the SOI ecosystem in China – the presentation then goes on to detail who does what. [caption id="attachment_12306" align="alignleft" width="1000"] (Courtesy: Simgui and SOI Consortium)[/caption] Inspection and Metrology Relevance in SOI Manufacturing, Jijen Vazhaeparambil, Vice President General Manager, KLA-Tencor. [caption id="attachment_12305" align="alignleft" width="300"] (Courtesy: KLA-Tencor and SOI Consortium)[/caption] K-T has played a strategic role in the SOI story going back for decades (and in fact they wrote a piece for the third edition of ASN back in 2005!), ensuring metrology innovations for things that hadn't previously need detection and measurement. With each new set of requirements, they rose to the occasion with wafer metrology solutions that helped increase quality and decrease costs. This presentation recaps some of them.
Read More
Sensors are inextricably linked to the future requirements of partially and fully autonomous vehicles. From highly granular dead-reckoning subsystems that rely on industrial-strength gyroscopes for superior navigation to more intelligent and personalized cockpits featuring intuitive human machine interfaces (HMIs) and smart seats, new generations of partially and fully autonomous cars will use sensors to enable dramatically better customer experiences.Dead reckoning, or, where am I, exactly? Dead reckoning is the process of calculating one’s current position by using a previously determined position, and advancing that position based upon known speeds over a time slice. As a highly useful process, dead reckoning is the basis for inertial navigation systems in aerospace navigation and missile guidance, not to mention your smartphone.Today’s best-in-class MEMS gyroscopes can offer 30-50 cm resolution (this is the yaw rate drift) over a distance of 200 meters — a typical tunnel length where a GPS signal is lost. For semi-autonomous (L3) or autonomous (L4, L5), the locational accuracy is well below 10 centimeters; that’s an accuracy usually reserved for high-end industrial or aerospace gyroscopes with a raw bias instability ranging from 1°/h and down to 0.01°/h. These heavy-duty gyros command prices from $100s up to $1000s. Current performance levels of different gyroscopes by application and performance measure in terms of bias drift (IHS Markit). This poses an interesting potential opportunity for both industrial-performance MEMS-based gyroscope sensor-makers, such as Silicon Sensing Systems, Analog Devices, Murata, Epson Toyocom and TDK InvenSense, and for broader-based sensor component-makers such as Bosch, Panasonic, STMicroelectronics, and TDK (InvenSense and Tronics).While MEMS can master performance, size and low weight, cost remains the challenge. The fail-operational mode requirement for autonomous driving will accommodate higher prices, at least in the beginning, probably in the $100+ range at first, even for the relatively low volumes of self-driving cars anticipated by 2030. Nonetheless, automotive volumes are very attractive compared to industrial applications and offer a lucrative future market for dead-reckoning sensors.Your cockpit will get smarter Automakers are banking on the idea that people like to control their own physical environment. Interiors already feature force and pressure sensors that provide more personalized seating experiences and advanced two-stage airbags for improved safety. In some vehicles, automakers are using pairs of MEMS microphones for noise reduction and image or MEMS infrared sensors for detection of driver presence. Eventually, we might see gas sensors that monitor in-cabin CO2 levels, triggering a warning when they detect dangerous levels that could cause drowsiness. These smart sensors would then “tell” the driver to open the window or activate an air-scrubbing system in a more complex solution. While today’s CO2 sensors are still relatively expensive, we may see them designed-in as lower-cost versions come to market.Future cockpits will need to go beyond such concepts in the lead-up to fully automated driving. Seats could contain sensitive acceleration sensors that measure heart and respiration rates as well as body movement and activity. Other devices could monitor body humidity and temperature.We need look no further than Murata, a supplier initially targeting hospital beds with a MEMS accelerometer as a replacement for pulse oximeters. That same Murata accelerometer could be placed potentially in a car seat to detect heart rate. It’s not the only way to do this: another sensing approach for heart-rate measurement comprises millimeter wave radiation, a method that can even look through objects such as books and magazines.Augmenting sensor-based body monitoring, automotive designers will use cameras to fuse information such as gaze direction, rate of blinking and eye closure, head tilt, and seat data with data gathered by sensors to provide valuable information on the driver’s physical condition, awareness and even mood. Faurecia’s Active Wellness concept—unveiled at the 2016 Paris Motor Show—proves that this technology might be coming sooner than we think. Active Wellness collects and analyzes biological data and stores the driver’s behavior and preferences. This prototype provides data to predict driver comfort based on physical condition, time of day, and traveling conditions, as well as car operating modes: L3, L4 or L5. Other features such as event-triggered massage, seat ventilation and even changes in ambient lighting or audio environment are possible. Faurecia’s “cockpit of the future,” announced at CES 2018. (Faurecia) Meanwhile, there are other commercial expressions of more advanced HMI as well as plenty of prototypes. Visteon’s Horizon cockpit can use voice activation and hand gestures to open and adjust HVAC. Capacitive sensors are already widely used for touch applications, and touchless possibilities range from simple infrared diodes for proximity measurement to sophisticated 3D time-of-flight measurements for gesture control.Clearly, automotive designers will have a lot more freedom with HMI in the cabin space, providing a level of differentiation that manufacturers think customers will appreciate—and for which they will pay a premium.Managing sensor proliferationResearchers are investigating ways to solve the issue of high-functionality vehicles containing myriad sensing inputs, i.e., when we have so many sensing inputs, designers must address wiring complexity and unwanted harness weight. Faurecia, for example, is considering ways to convert wood, aluminum, fabric or plastic into smart surfaces that can be functionalized via touch-sensitive capacitive switches integrated into the surface. These smart surfaces could reduce the explosion of sensing inputs, thereby diminishing wiring complexity. With availability from 2020, Faurecia’s solutions are approaching the market soon.Beyond functionalized switches, flexible electronics and wireless power sources, and even energy harvesting (to mitigate power sources), could provide some answers. Indeed, recent research has shown that graphene-based Hall-effect devices can be embedded in large-area flexible Kapton films, and eventually integrated into panels. OEMs such as Jaguar Land Rover are interested in such approaches to address the downsides of electronics and sensor proliferation, especially in luxury vehicles. While smart surfaces would represent a big change in sensor packaging and a disruption in current semiconductor processes, they remain a long way from commercial introduction.By 2030 or thereabouts, fully autonomous cars that detect our mood, vital signs and activity level could well be available. Cabins could signal us to open the window if CO2 levels become dangerous. HVAC systems could increase seat ventilation or turn up the air conditioning (or the heat) based on our body temperature. Feeling too hot or too cold in the cabin could become a thing of the past, at least for the driver, whose comfort level is the most important! We could feasibly feel more comfortable in the car than in our office, our home or at the movies. Perhaps our car will become our office, our entertainment center and our home away from home as we take long road trips with the family, without a single passenger uttering, “Are we there yet?” Bio: Richard Dixon, Ph.D., is a senior principal analyst for MEMS research at IHS Markit and author of more than 50 MEMS-related consulting and market research studies. He is a renowned expert on automotive MEMS and magnetic sensors used in safety, powertrain and body applications. Along with supporting the overall activities of the MEMS and sensors group, his responsibilities include the development of databases that forecast the markets for more than 20 types of silicon-based sensors in more than 100 automotive applications. In addition, he has supported organizations with future scenarios for sensors in cars and has supported many custom projects for companies in the automotive supply chain.In his prior post at Wicht Technologie Consulting (WTC), Dixon was a senior MEMS analyst where he led research on physical sensors and was the co-author of the NEXUS Task Force Report for MEMS and Microsystems 2005-2009. He has also led commercialization and road-mapping activities on European Commission-funded technology projects, including detailed MEMS chip cost analysis studies.Dixon worked previously as a journalist in the compound semiconductor industry and has five years of experience as a technology transfer professional at RTI International, where he provided business and market intelligence for early-stage technologies.Dixon graduated from University of Greenwich with a degree in materials science and earned a doctorate from Surrey University in semiconductor characterization. He speaks English and German.For more information, visit https://technology.ihs.com/Categories/450486/mems-sensors. ___________________________________________________________________________________________________ Want to hear more from IHS Markit on MEMS and sensors devices and their applications? Top thinkers from IHS Markit will be speaking at upcoming SEMI events. Register today!Disruption in the authentication sensor market Manuel Tagliavini, Principal Analyst, MEMS Sensors, IHS Markit Autonomous and Electric Cars: What's in for Conventional MEMS SensorsJeremie Bouchaud, Director and Senior Principal, MEMS Sensors, IHS Markit
Read More
Are you ready for a shared economy where your transportation needs are no longer met by an automaker, but rather a “mobility service provider”? While smart transportation news has mostly focused on the likes of electrification (Tesla) and autonomy (Waymo), the real changes in transportation may be more fundamental than self-driving electric cars. According to presenters at this week’s Smart Automotive Summit at SEMICON Taiwan, new technologies won’t just make cars smarter: they will transform the way we see and use transportation in myriad ways.Constance Chen, public relations general manager for forum sponsor Mercedes Benz, opened with a brief overview of parent Daimler’s evolving approach to transportation, dubbed CASE, which stands for Connected, Autonomous, Shared and Services, and Electric.“The fundamental value of vehicles is changing,” Chen said, and car ownership is one of the biggest changes. Ride-sharing services like Uber and Lyft, and shared car services like ZipCar and DriveNow, are already addressing the transportation needs of a growing urban population that eschews car ownership. Traffic congestion, parking challenges, and a desire to improve air quality are key drivers (no pun intended) moving people away from car ownership to embrace shared transportation solutions.Indeed, societal considerations are as challenging as some technological hurdles facing autonomous vehicle development. Robert Brown, Taiwan operations manager for Magma Electronics, listed his top five challenges for autonomous transportation: Perception (vision, sensors) Assessment (ability of systems to analyze data) Control (need for faster-than-human response) Communication (vehicle-to-vehicle, vehicle-to-everything) Expectations—specifically people’s expectations of the value autonomous transportation should deliver As people change the way they view transportation and begin to understand what is possible when they can relinquish control of their vehicle, they’re transportation needs and expectations are likely to change. The challenges are, of course, also an opportunity to deliver a wide range of services, including information, entertainment, and retail, which opens the door for traditional carmakers to position themselves more as service providers like Mercedes Benz.For those who have grown up with traditional car ownership and the perceived freedom that owning allows one to go anywhere at anytime, the idea of giving up their car—one that they drive themselves—might seem beyond the pale. But as ride-sharing services are already showing, a growing portion of our population seems more than ready to embrace a shared and autonomous future.The SEMICON Taiwan Smart Automotive Summit is part of SEMI’s Smart Transportation initiative focusing on automotive electronics, a top priority for SEMI and its 2,000+ members. SEMI’s industry standards, technology communities, roadmap efforts, EH S/regulatory activities and other global platforms and communities bring together the automotive and semiconductor supply chains to collaborate, increase cross-industry efficiencies and shorten the time to better business results.Michael Droeger is director of marketing at SEMI.
Read More
2017 was a good year for the MEMS and sensors business, and that upward trend should continue. We forecast extended strong growth for the sensors and actuators market, reaching more than $100 billion in 2023 for a total of 185 billion units. Optical sensors, especially CMOS image sensors, will have the lion’s share with almost 40 percent of market value. MEMS will also play an important role in that growth: During 2018–2023, the MEMS market will experience 17.5 percent growth in value and 26.7 percent growth in units, with the consumer market accounting for more than 50 percent(1) share overall. Evolution of SensorsSensors were first developed and used for physical sensing: shock, pressure, then acceleration and rotation. Greater investment in R D spurred MEMS’ expansion from physical sensing to light management (e.g., micromirrors) and then to uncooled infrared sensing (e.g., microbolometers). From sensing light to sensing sound, MEMS microphones formed the next wave of MEMS development. MEMS and sensors are entering a new and exciting phase of evolution as they transcend human perception, progressing toward ultrasonic, infrared and hyperspectral sensing.Sensors can help us to compensate when our physical or emotional sensing is limited in some way. Higher-performance MEMS microphones are already helping the hearing-impaired. Researchers at Arizona State University are among those developing cochlear implants — featuring piezoelectric MEMS sensors — which may one day restore hearing to those with significant hearing loss. The visually impaired may take heart in knowing that researchers at Stanford University are collaborating on silicon retinal implants. Pixium Vision began clinical trials in humans in 2017 with its silicon retinal implants.It’s not science fiction to think that we will use future generations of sensors for emotion/empathy sensing. Augmenting our reality, such sensing could have many uses, perhaps even aiding the ability of people on the autism spectrum to more easily interpret the emotions of others.Through my years in the MEMS industry, I have identified three distinct eras in MEMS’ evolution: The “detection era” in the very first years, when we used simple sensors to detect a shock. The “measuring era” when sensors could not only sense and detect but also measure (e.g., a rotation). The “global-perception awareness era” when we increasingly use sensors to map the environment. We conduct 3D imaging with Lidar for autonomous vehicles. We monitor air quality using environmental sensors. We recognize gestures using accelerometers and/or ultrasonics. We implement biometry with fingerprint and facial recognition sensors. This is possible thanks to sensor fusion of multiple parameters, together with artificial intelligence. Numerous technological breakthroughs are responsible for this steady stream of advancements: new sensor design, new processes and materials, new integration approaches, new packaging, sensor fusion, and new detection principles.Global Awareness SensingThe era of global awareness sensing is upon us. We can either view global awareness as an extension of human sensing capabilities (e.g., adding infrared imaging to visible) or as beyond-human sensing capabilities (e.g., machines with superior environmental perception, such as Lidar in a robotic vehicle). Think about Professor X in Marvel’s universe, and you can imagine how human perception could evolve in the future! Some companies envisioned global awareness from the start. Movea (now part of TDK InvenSense), for example, began their development with inertial MEMS. Others implemented global awareness by combining optical sensors such as Lidar and night-vision sensors for robotic cars. A third contingent grouped environmental sensors (gas, particle, pressure, temperature) to check air quality. The newest entrant in this group, the particle sensor, could play an especially important role in air-quality sensing, particularly in wearable devices.Driven by increasing societal concern over mounting evidence of global air-quality deterioration, air pollution has become a major topic in our society. Studies show that there is no safe level of particulates. Instead, for every increase in concentration of PM10 or PM2.5 inhalable particles in the air, the lung cancer rate is rising proportionately. Combining a particle sensor with a mapping application in a wearable could allow us to identify the locations of the most polluted urban zones.The Need for Artificial Intelligence To realize global awareness, we also need artificial intelligence (AI), but first, we have challenges to solve. Activity tracking, for example, requires accurate live classification of AI data. Relegating all AI processing to a main processor, however, would consume significant CPU resources, reducing available processing power. Likewise, storing all AI data on the device would push up storage costs. To marry AI with MEMS, we must do the following: Decouple feature processing from the execution of the classification engine to a more powerful external processor. Reduce storage and processing demands by deploying only the features required for accurate activity recognition. Install low-power MEMS sensors that can incorporate data from multiple sensors (sensor fusion) and enable pre-processing for always-on execution. Retrain the model with system-supported data that can accurately identify the user’s activities. There are two ways to add AI and software in mobile and automotive applications. The first is a centralized approach, where sensor data is processed in the auxiliary power unit (APU) that contains the software. The second is a decentralized approach, where the sensor chip is localized in the same package, close to the software and the AI (in the DSP for a CMOS image sensor, for example). Whatever the approach, MEMS and sensors manufacturers need to understand AI, although they are unlikely to gain much value at the sensor-chip level.Heading to an Augmented WorldWe have achieved massive progress in sensor development over the years and are now reaching the point when sensors can mimic or augment most of our perception: vision, hearing, touch, smell and even emotion/empathy as well as some aesthetic senses. We should realize that humans are not the only ones to benefit from these developments. Enhanced perception will also allow robots to help us in our daily lives (through smart transportation, better medical care, contextually aware environments and more). We need to couple smart sensors’ development with AI to further enhance our experiences with the people, places and things in our lives.About the authorWith almost 20 years’ experience in MEMS, sensors and photonics applications, markets, and technology analyses, Dr. Eric Mounier provides in-depth industry insight into current and future trends. As a Principal Analyst, Technology Markets, MEMS Photonics, in the Photonics, Sensing Display Division, he contributes daily to the development of MEMS and photonics activities at Yole Développement (Yole). He is involved with a large collection of market and technology reports, as well as multiple custom consulting projects: business strategy, identification of investment or acquisition targets, due diligence (buy/sell side), market and technology analyses, cost modeling, and technology scouting, etc.Previously, Mounier held R D and marketing positions at CEA Leti (France). He has spoken in numerous international conferences and has authored or co-authored more than 100 papers. Mounier has a Semiconductor Engineering Degree and a PhD in Optoelectronics from the National Polytechnic Institute of Grenoble (France).Mounier is a featured speaker at SEMI-MSIG European MEMS Sensors Summit, September 20, 2018 in Grenoble, France. (1) Source: Status of the MEMS Industry report, Yole Développement, 2018
Read More
At a Glance “Software is eating the world ... and AI is eating software.” Amir Husain, author of The Sentient Machine, at SEMICON West 2018 We’re living in a digital world where semiconductors have been taken for granted. But, Artificial Intelligence (AI) is changing everything – and bringing semiconductors back into the deserved spotlight. AI’s potential market of hundreds of zettabytes and trillions of dollars relies on new semiconductor architectures and compute platforms. Making these AI semiconductor engines will require a wildly innovative range of new materials, equipment, and design methodologies. Moore’s Law carried us the past 50-plus years and as we’re now stepping into the dawn of AI’s potential, we can see that the coming Cognitive Era will drive its own exponential growth curve. This is great for the world – virtually every industry will be transformed, and people’s lives will get better – and it’s fantastic for our industry. This truly is the very best time to be working in our industry. I’m excited to be at SEMI in this inflection period and at the center of the collaborative platforms that bring the electronics manufacturing supply chain together to Connect, Collaborate, and Innovate to realize the new Cognitive Era. I invite you to partner with SEMI in building the foundation for the Cognitive Era to increase the growth and prosperity of our industry. The World Wakes Up Our lives have become digital. An Amazon Echo wakes us up and answers questions about the weather and traffic. Google Maps tells us the best way to get to a meeting. Yelp finds the best nearby restaurant. A Tweet now even informs us of the latest change in government policy. It’s a digital world that we live in – and the world already takes it for granted. We in the industry know that the digital world only works because of the semiconductors we make and because of our integrated electronics manufacturing supply chain. We make the materials and equipment that, in turn, make the chips that become the beating hearts of the digital economy. But, semiconductors have been largely invisible – hidden away under and inside a smart speaker, locked deep within a phone, buried in data centers and out of view. Meanwhile, the internet companies like Google, Amazon, Alibaba, Tencent, and Facebook stole the meaning of “Tech” and were given most of the credit for our digital world. But, finally, things are changing – it’s all coming back to semiconductors! AI Changing Everything Over $400B in semiconductors were sold in 2017 – those unseen chips like hearts beating away in Apple computers, in mobile phones for online shopping and social media, and in televisions showing Netflix. Now internet companies Alphabet, Alibaba, Amazon, Facebook, Microsoft and others are rushing to develop their own chips. Silicon is back in the Silicon Valley! Hardware is, once again, the place to be. Why? We are now entering the epoch of Artificial Intelligence (AI) – and semiconductors, and new compute architectures, are the key to AI. At this moment, hardware, not software, is the AI enabler to make leaps in performance and to usher in new architectures to become brain-like with neural networks. Beyond major AI chip investments like Google’s (Alphabet) $300M+ program to develop its Tensor Processing Unit (TPU) chip, there’s been a surge in new chip startups and VC funding. Last year, VCs (with corporate investors) invested more than $1.5B in new AI chip startups – doubling the rate from the prior year. After years of consolidation, there is, as some have described, a “Cambrian Explosion” of semiconductor startups with names like Cerebras, Graphcore, Wave Computing, Horizon Robotics, Cambricon Technologies, and DeePhi from the US, Europe, and China. Cambricon (China) has already become the first AI chip “Unicorn” (startup valued $1B+) with a valuation of more than $2.5B after their recent Round B financing. It’s a new silicon world and a new race, as Cade Metz (The New York Times, 1/14/2018) said, “… everyone is starting from the same place: the beginning of a new market.” Winning at AI is very big business. John Kelly, SVP Cognitive Solutions and Research at IBM, in his SEMICON West keynote earlier this month, said, we’re in the era of Artificial Intelligence with more than a $2T opportunity for AI decision making support on top of the $1.5T IT business in 2025. McKinsey estimates deep learning could account for between $3.5T and $5.8T in annual value. As John Kelly presented, AI will transform entire industries – not just our personal devices and lives. The $2T AI decision making support opportunity in 2025 is projected to transform the major economy industries as follows: Source IBM Market Development Insights Analysis; Oxford economics, CapitalIQ, McKinsey Global Institute Moore’s Law describes the exponential increase in the number of transistors per area that has driven growth, and has been the engine for digital innovation, through first the computer era and then the mobility era and now into the dawn of the data era. While the Dennard scaling approach to Moore’s Law may be slowing, the data-centric era continues to drive demand and the industry continues to find new ways to pack more transistors into less volume. Chip sales are forecast to pass $0.5T in 2019 and I predict they will surpass $1T before 2030. It turns out the Smart is not enough – we must reach “Beyond Smart.” Beyond Smart – The Cognitive Era As we move further into the data-centric age, we see it is more than Big Data and AI, it is, instead, the dawn of a wholly new cognitive era. SEMICON West’s 2018 theme was “Beyond Smart” because we are standing at the inflection from sensors triggering actions (smart) to systems that learn and make decisions (cognitive). Devices are moving “beyond smart” to being “cognitive or aware.” Gary Dickerson (CEO of Applied Materials) at SEMICON West said, “… we are in the beginning of the first inning of a major inflection.” Even in the early dawn of the cognitive era, the volume of data is simply astonishing. In the last 24 months, we create more than 90% of all historic digital data. By 2025 we expect AI to generate 160 zettabytes – with 80% of that unstructured data. Moore’s Law is an exponential, but as John Kelly points out, AI’s deep learning is driving its own exponential with performance/watt increasing 2.5X each year. Source: IBM AI was the focus of SEMICON West’s Day 1 keynotes – and a common theme through much of the events programming. There was a common language in the keynotes by John Kelly, Gary Dickerson, and William Dally (Chief Scientist and SVP of Research NVIDIA), and others. We heard how AI is based on data, algorithms, and compute. I was inspired by these talks and for the potential for AI and the cognitive era. Looking ahead, I believe data + algorithms + compute + machine learning = knowledge and cognition. My vision is that this AI knowledge and cognition will be the catalyst to create new modes of systems transformations that will usher in the next Industrial Revolution. As the 4th Industrial Revolution becomes a reality, I look forward to working with others in SEMI Think Tanks to imagine the 5th Industrial Revolution – and its opportunities for our industry. I believe that it will make our lives better, healthier, more prosperous, and more fulfilled. A sentiment shared by many speakers at SEMICON West was – this is the most exciting time to be in the semiconductor manufacturing industry. Many wished they were just now starting in the industry as this is the most interesting inflection and transformation ever. There is a flood of new architectures, new materials, new equipment, new processes – and a new system-based design approach to enable the Cognitive Era. We, in hardware manufacturing, are in the driver’s seat for this incredible ride. SEMI is working to help its members speed their time to better business results – and to take full advantage of the Cognitive Era and AI opportunity. At SEMICON West 2018, SEMI provided a broad and deep slate of program education and spotlighted AI expertise across the electronics manufacturing supply. In case you missed it, SEMI also provided: Seven keynotes and dozens of expert panelists Semiconductor venture funding program – problems and solutions for the ecosystem SEMI Smart Workforce Pavilion with over 600 students registered to learn about the industry Smart Pavilions including Smart Manufacturing and Smart Automotive SEMI highlighted the five key vertical application platforms where our industry needs to collaborate across the full supply chain and streamline the supply chain for efficiency. The five are: IoT, Smart Transportation, Smart Manufacturing, Smart MedTech, and Smart Data. These verticals drive huge business potential and are just one of the reasons that SEMICON West has become the gathering place of the extended electronics manufacturing supply chain. With SEMI, together we can realize the potential of the coming Cognitive Era. SEMI members can advance the industry with SEMI collective action in Workforce Development, Advocacy (public policy and regulatory), Standards to synchronize the industry, and in the many SEMI technology communities and special interest groups – to increase the global industry’s rate of growth and overall level of prosperity. For more information, please visit semi.huihuidehui.workers.dev; to become a member, please visit http://semi.huihuidehui.workers.dev/en/become-member-join-semi. Ajit Manocha is President and CEO of SEMI
Read More